

While the S&P 500 is up 17.5% since April 2026, Stratasys (currently trading at $8.57 per share) has lagged behind, posting a return of 6.8%. This may have investors wondering how to approach the situation.
Is now the time to buy Stratasys, or should you be careful about including it in your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Is Stratasys Not Exciting?
We’re cautious about Stratasys. Here are three reasons why there are better opportunities than SSYS, plus one stock we’d rather own.
1. Long-Term Revenue Growth Flatter Than a Pancake
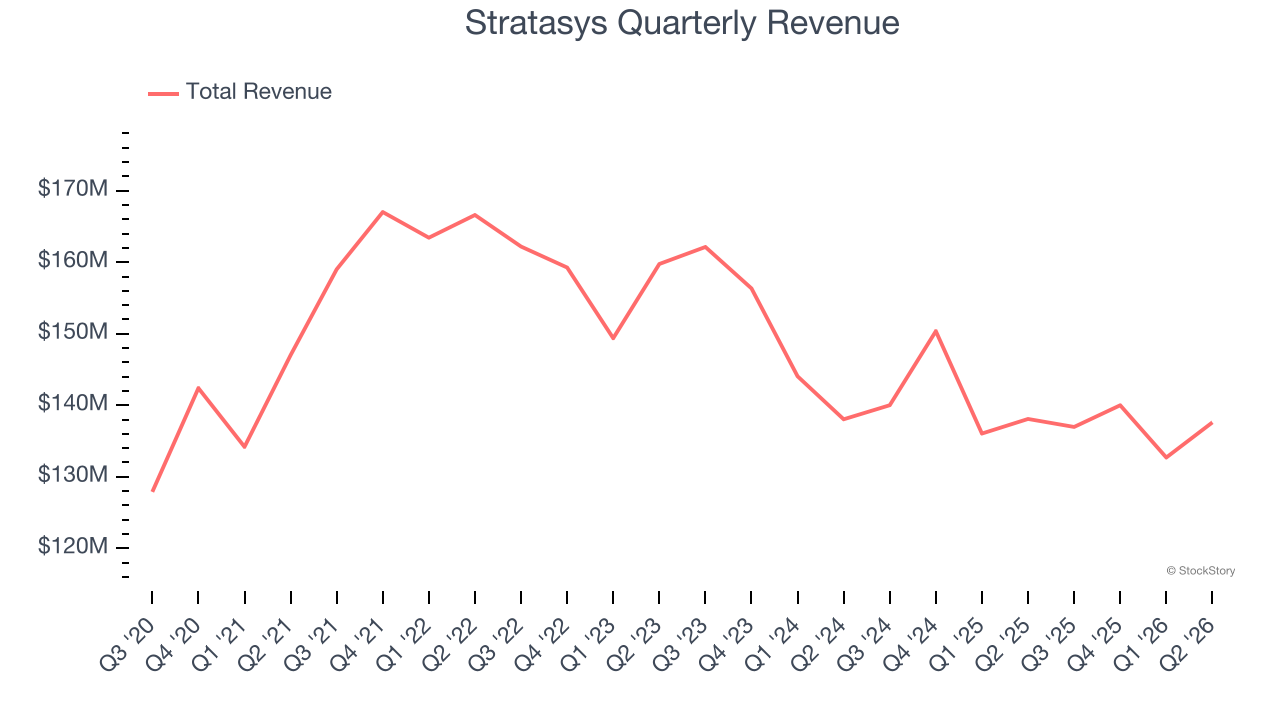
A company’s long-term performance is an indicator of its overall quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years. Unfortunately, Stratasys struggled to consistently increase demand as its $547.3 million of sales for the trailing 12 months was close to its revenue five years ago. This was below our standards and is a sign of lacking business quality.
2. Operating Losses Sound the Alarm
Operating margin is a key measure of profitability. Think of it as net income - the bottom line - excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
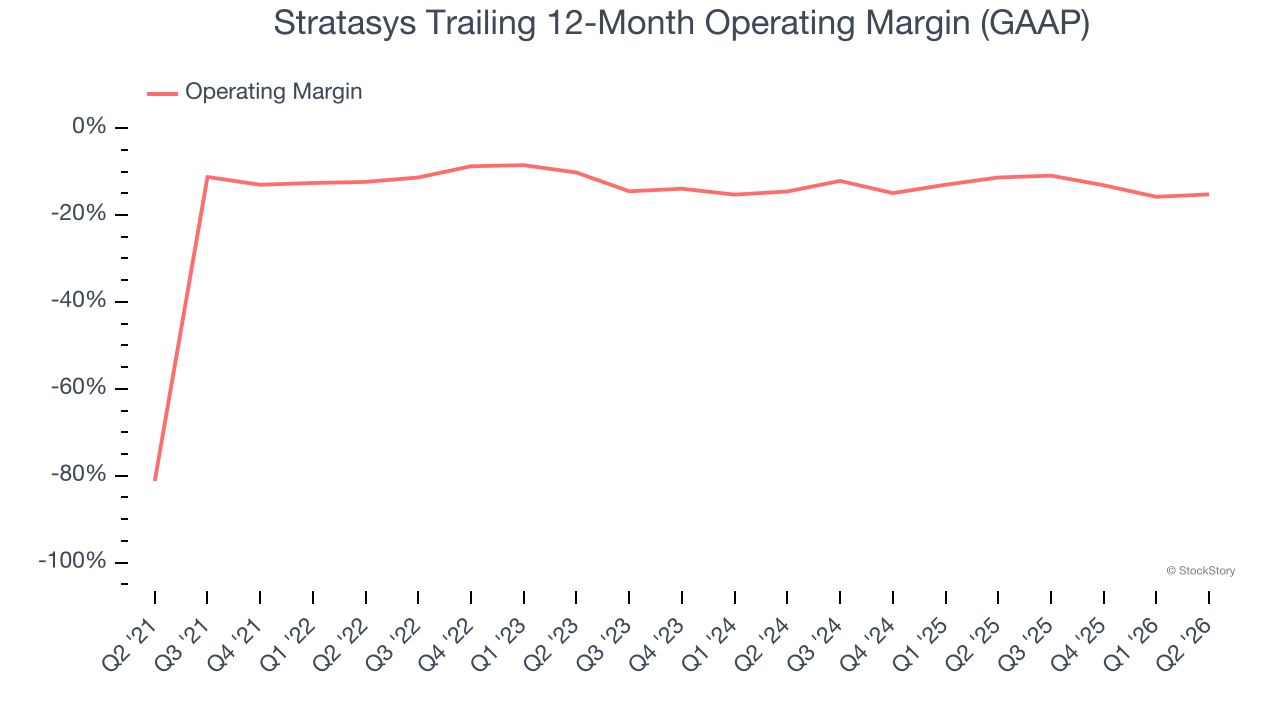
Stratasys’s high expenses have contributed to an average operating margin of negative 12.7% over the last five years. Unprofitable industrials companies require extra attention because they could get caught swimming naked when the tide goes out. It’s hard to trust that the business can endure a full cycle.
3. Cash Burn Ignites Concerns
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
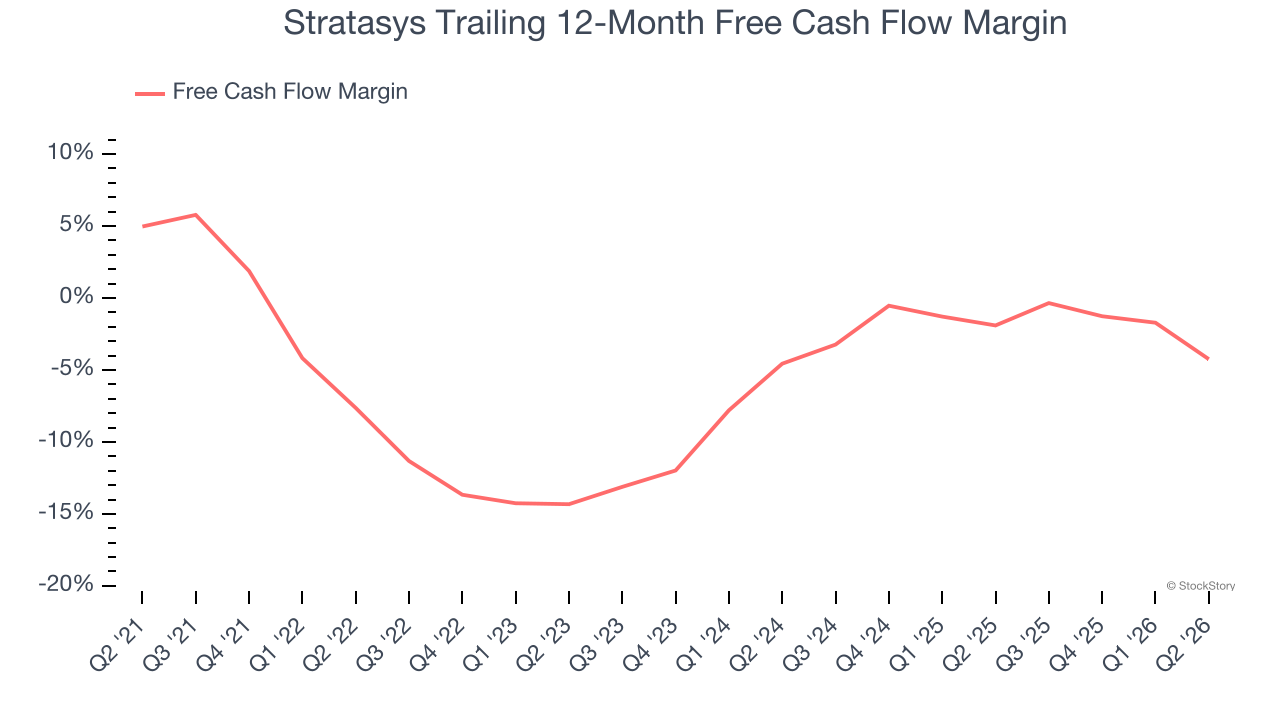
Stratasys’s demanding reinvestments have drained its resources over the last five years, putting it in a pinch and limiting its ability to return capital to investors. Its free cash flow margin averaged negative 6.7%, meaning it lit $6.73 of cash on fire for every $100 in revenue.
Final Judgment
Stratasys isn’t a terrible business, but it isn’t one of our picks. With its shares trailing the market in recent months, the stock trades at 61.3× forward P/E (or $8.57 per share). This multiple tells us a lot of good news is priced in - we think other companies feature superior fundamentals at the moment. We’d suggest looking at a top digital advertising platform riding the creator economy.
High-Quality Stocks for All Market Conditions
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.